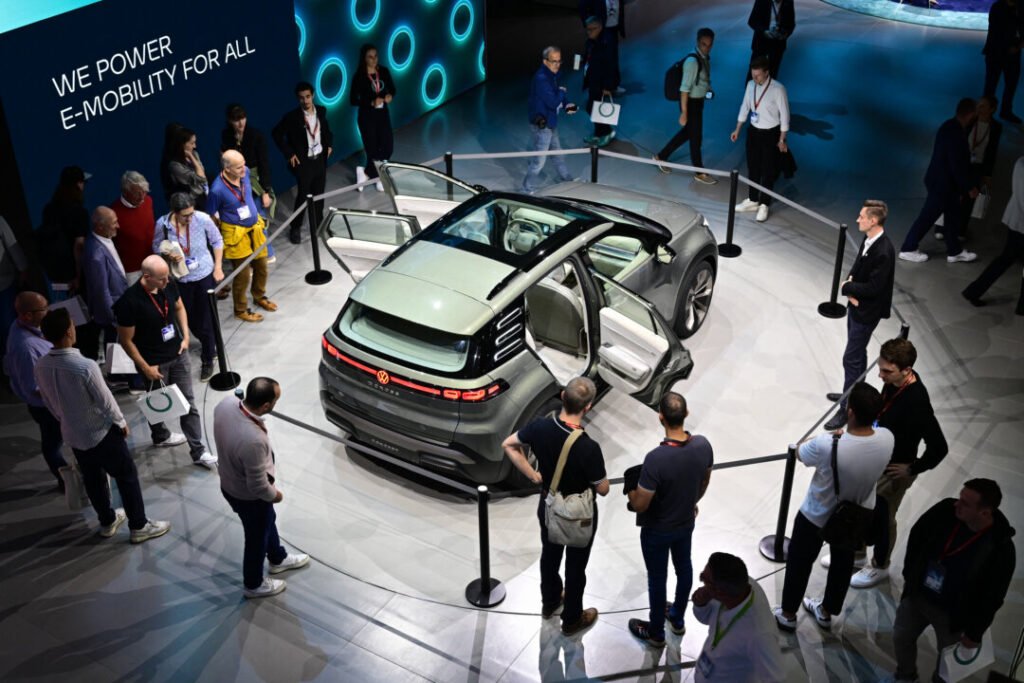
As Chinese automakers gain ground in Europe, the continent’s car industry is grappling with falling production, mounting job losses, and a growing debate over whether it can compete with Chinese rivals or must increasingly partner with them to secure its future.
The European Union (EU) automotive industry supports about 13 million jobs and contributes roughly 7 percent of the EU’s GDP, but intensifying global competition, particularly from China, is prompting manufacturers to rethink their business models.
This includes partnerships with Chinese automakers, as European companies seek to preserve one of the EU’s industrial pillars.
Last year, the European Commission (EC) described the sector as being at a “critical turning point.”
In its March 2025 Automotive Action Plan, the EC warned that the industry faced high costs, supply-chain vulnerabilities, and the risk that European companies could fall behind in batteries, software, infotainment, and autonomous driving.
The EC also pointed to overseas competitors benefiting from assertive industrial strategies and state support. Europe’s biggest carmakers have echoed those concerns.
Related Stories

In July, Renault Group said the industry’s biggest challenge was “a significant competitiveness gap” separating the EU from China in development times and production costs.
The company said lower labor costs and Asia’s aggressive vertical integration of battery technologies were forcing legacy automakers to rethink their industrial models.
German automaker BMW struck a similar tone in its 2025 annual report, concluding that growing competition, particularly in China, was making long-term planning increasingly difficult.

A worker performs a final check on new Volkswagen ID.3 electric cars at the Volkswagen plant in Dresden, Germany, on May 14, 2025. Sean Gallup/Getty Images
Pierre-Olivier Essig, founder and head of research at independent investment research firm AIR Ltd, told The Epoch Times that for Europe to remain competitive, it should focus on areas where its automakers retain a competitive advantage.
These include luxury and performance vehicles, he said, while governments consider measures to support domestic manufacturing.
“There’s two types of subsidies, but they need to help them,” Essig said.
“You help the companies building cars in your country. You need to find a way of letting them pay less taxes on employees or on the profits. Then you have subsidies to help consumers buy the cars.
“If they don’t do that, they’re going to be like a service-only country. You just kill your industry.”
Without greater support for domestic manufacturers, Essig warned Europe risked becoming “a service-only country.”
China’s Growing Presence
China’s growing presence in Europe’s automotive market and the EU’s reliance on Beijing has accelerated in recent years.
According to a March analysis by the European Commission, China overtook the EU as the world’s largest car exporter in 2024, while Chinese vehicles accounted for 17 percent of the total value of cars imported into the EU.
The report warned Chinese brands could gain further ground if European manufacturers fail to close a widening innovation gap, particularly in digital technologies.
Kyle Peacock, principal at Peacock Tariff Consulting, said those figures only tell part of the story.
“‘Chinese-made’ is an origin measure, not a brand measure,” Peacock told The Epoch Times. “A good share of that 17 percent of import value is Western original equipment manufacturer output built in China: Tesla’s Shanghai Model 3, BMW’s iX3, the Dacia Spring.”

A man checks the BMW iX3 electric concept car during a media preview at the Auto China 2018 motor show in Beijing on April 25, 2018. Jason Lee/Reuters
Peacock added that the numbers overstate Chinese brand penetration and understate how deeply European makers already rely on China themselves.
The EU imposed additional anti-subsidy duties of up to 35.3 percent on Chinese battery electric vehicles (BEVs) exports, on top of its standard 10 percent import tariff, after concluding that Chinese manufacturers had benefited from unfair state support.
Even so, European car manufacturers said in May that Chinese-made vehicles accounted for 7 percent of total EU car sales last year.
Their presence was even more pronounced in electric vehicles, representing 20 percent of BEV sales and 12 percent of plug-in hybrid sales, according to the European Automobile Manufacturers’ Association (ACEA).
Peacock said those figures understated the scale of the competitive challenge because Chinese manufacturers were gaining ground primarily in the affordable electric vehicle segment, where many European automakers struggle to build profitable models.
“The advantage is not mainly subsidy,” Peacock said. “It is LFP cell cost, vertical integration down to cells and power semiconductors, 18 to 24 month development cycles against Europe’s 40 to 48, and scale across a 25 million unit home market. A duty rate touches none of that.” LPF refers to lithium iron phosphate battery cells.
Pressure on Production
The pressure is now being reflected in Europe’s factories as well as its vehicle sales.
ACEA data show EU passenger car production fell 6.2 percent in 2024 to 11.4 million vehicles before declining another 2.8 percent year over year during the first half of 2025 to under 6 million vehicles.

Workers assemble a Volkswagen ID.3 electric car on a production line at the Volkswagen electric car factory in Zwickau, Germany, on Oct. 13, 2025. Jens Schlueter/Getty Images
Suppliers have been hit particularly hard.
CLEPA, known in English as the European Association of Automotive Suppliers, said in January that automotive suppliers announced 104,000 job cuts across 2024 and 2025, reflecting mounting structural pressures on the industry.
In March, the organization warned that Europe’s long-standing position as a global automotive manufacturing powerhouse was rapidly eroding.
“China’s automotive supply industry is growing faster than ever, increasingly challenging Europe’s suppliers,” said CLEPA Secretary General Benjamin Krieger. “If Europe wants to remain a major manufacturing hub, we need policies that strengthen our competitiveness and ensure that suppliers can compete on a true level playing field.”
Searching for a Way Forward
The debate in Europe has increasingly shifted from how to shield domestic manufacturers from Chinese competition to whether Chinese investment itself could help preserve the continent’s automotive industry.
Chinese automakers are steadily expanding their manufacturing footprint in Europe. Chery assembles vehicles in Barcelona, while Xpeng has contracted Magna Steyr to build vehicles in Austria.

Attendees look at a BYD Dolphin during the 2022 Central China International Auto Show in Wuhan, Hubei Province, China, on July 14, 2022. Getty Images
Leapmotor plans to begin production in Spain later this year, and BYD is preparing to start mass production at its Hungarian plant by the end of the year.
At the same time, several European automakers have begun partnering with Chinese companies to utilize underused manufacturing capacity and strengthen local supply chains.
Those partnerships include Stellantis’s joint venture with Dongfeng in Europe, while Ford has agreed to collaborate with Geely at a Spanish plant.
Speaking at the Automotive News Europe Congress in June, Renault Chief Executive François Provost said the EU should encourage Chinese automakers to source more components locally rather than simply assemble vehicles in Europe, adding that most of the value in automotive production comes from parts manufacturing.
Partnerships between European and Chinese manufacturers, according to Essig, are becoming increasingly difficult to avoid.
“Renault is trying to do it too. Stellantis because they were so late they had no choice outside partnering with Chinese automakers,” Provost said. “It’s getting very difficult to say, for a car built in Europe, what originates from Germany, France, or China. The mix is getting bigger every year.”
Not all European industry groups agree on the way forward. In July, Germany’s automotive industry association (VDA) said Europe should open underused factories to foreign automakers to help keep plants running and protect jobs.
Italy’s automotive industry has taken a tougher approach.
In September, the head of Italian auto suppliers lobby ANFIA, Roberto Vavassori, called for the EU to impose an 80 percent tariff on Chinese-made vehicles and parts above a set import threshold.
“We have maximum respect for what the Chinese industry has achieved,” he said. “But that respect has now turned into fear.”
Vavassori warned that Europe could not afford to lose an industry “essential for its strategic autonomy.”
Reuters contributed to this report.